Profit and Loss Statement: How to Read and Prepare One for a Small Business
A profit and loss statement shows whether your business made money over a period. Learn its lines, how to prepare a simple one, a worked example and what the numbers tell you.
On this page
Sales are up, the shop is busy, and yet there never seems to be much left at the end of the month. A profit and loss statement tells you why. It's a one-page summary of what the business earned and spent over a period, and the difference between them. You don't need to be an accountant to read one, and with good records you can prepare a simple version yourself every month.
What a profit and loss statement shows#
A profit and loss statement (P&L, or income statement) lists revenue and expenses for a period, such as a month or a year, and shows whether the business made a profit or a loss.
It answers one question: over this period, did the business earn more than it cost to run? It doesn't show what the business owns or owes; that's the balance sheet. And it doesn't show cash in the bank; that's the cash flow statement.
The lines, top to bottom#
- Revenue (sales): everything you invoiced or sold in the period, minus returns and discounts.
- Cost of goods sold (COGS): the direct cost of what you sold: stock, raw materials, direct labour on jobs.
- Gross profit = revenue minus COGS.
- Operating expenses: the costs of running the business regardless of sales: rent, salaries, marketing, internet, transport, software.
- Operating profit = gross profit minus operating expenses.
- Other items: interest on loans, bank charges, one-off gains or losses.
- Profit before tax, then tax, then net profit.
A worked example#
A small bakery's October:
| Line | RWF |
|---|---|
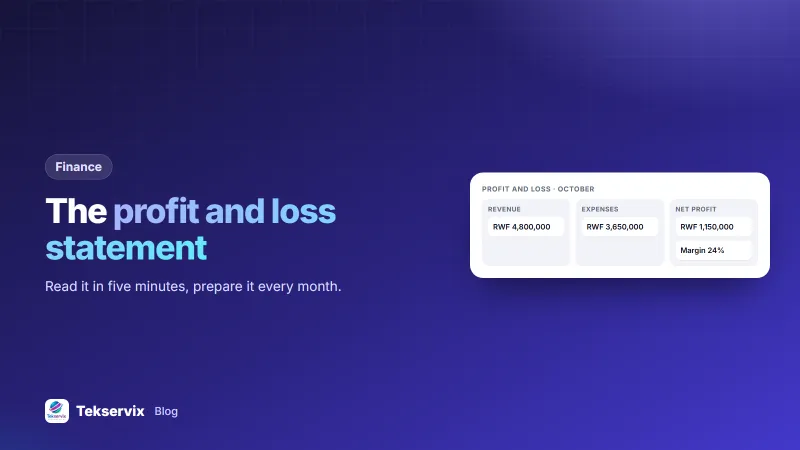
| Revenue | 4,800,000 |
| Cost of goods sold (flour, sugar, butter, packaging) | (1,900,000) |
| Gross profit | 2,900,000 |
| Rent | (600,000) |
| Salaries | (850,000) |
| Electricity and gas | (180,000) |
| Marketing | (70,000) |
| Transport and delivery | (50,000) |
| Operating profit | 1,150,000 |
The figures are illustrative. From them, the gross margin is 60% (2.9 million out of 4.8 million) and the operating margin about 24%. Before tax and loan interest, the bakery kept roughly RWF 240 for every RWF 1,000 of sales.
Margins that tell you something#
- Gross margin = gross profit ÷ revenue. If it falls, either your input costs rose or your prices didn't keep up. See how to price a product.
- Operating margin = operating profit ÷ revenue. It shows how efficiently the whole business runs.
- Expense ratios: each big expense as a share of revenue. Rent at 12% of sales is fine; rent at 35% is a problem.
Compare each month with the previous month and with the same month last year. Seasonal businesses in particular need the year-on-year view.
How to prepare one yourself#
- Pick the period: usually the calendar month.
- Total revenue from your invoices and sales records for that month.
- Total COGS: stock and materials used for those sales. For a shop, a simple method is opening stock + purchases − closing stock.
- Total operating expenses by category from your expense records. If you already track business expenses by category, this is a matter of adding up.
- Subtract in the order shown above.
- Write one sentence about what changed and why. That sentence is often more useful than the numbers.
The Tekservix Business Suite records income and expenses in one place and shows profit and loss for you, so the monthly report is ready when your records are.
Cash basis vs accrual basis#
On a cash basis, you count income when money arrives and expenses when you pay. It's simple and common for very small businesses. On an accrual basis, you count income when you invoice and expenses when you incur them, whether paid or not. It gives a truer picture of performance, especially if customers pay on credit, and it's what accountants use for larger businesses. Pick one and stick with it, so months are comparable. The IFRS standard on presenting financial statements sets out the formal rules if you need them.
Common mistakes#
- Mixing personal and business spending, which makes expenses meaningless.
- Counting loan money as revenue. A loan is money you owe, not income.
- Counting equipment purchases as a monthly expense. A laptop that lasts three years is spread over those years (depreciation). Ask your accountant how to treat large purchases.
- Forgetting the owner's time. If the business only makes a profit because you work unpaid, that's worth knowing.
- Ignoring small recurring costs that add up across the year.
Profit isn't cash#
A profitable month can still leave you short of cash if customers haven't paid their invoices, or if you bought extra stock for next month. Watch the P&L alongside your bank balance and receivables. Our guide to cash flow for small businesses covers that side.
How often to prepare one#
An annual profit and loss statement is enough for tax, but not for running a business. By the time you see the year's numbers, the months that lost money are long gone. A monthly statement, even a simple one, shows problems while you can still act on them: a supplier price rise eating into gross margin, a marketing spend that didn't bring sales, a slow month that needs a plan.
Set a date each month, such as the tenth, to close the previous month. Compare each month with the one before and with the same month last year, because many businesses are seasonal. After a year, you have twelve statements that tell the story of the business far better than one annual total.
Using it to decide#
A P&L is only useful if it changes what you do. Each month, choose one action from it: raise a price that no longer covers costs, drop a product with poor margins, renegotiate a big expense, or invest more in what's growing. Twelve small decisions a year, based on real numbers, add up to a noticeably healthier business.
Frequently asked questions
What is the difference between profit and cash?
Profit is income minus expenses for a period, including sales not yet paid for. Cash is the money actually in your account. A business can be profitable on paper and still run out of cash if customers pay late.
How often should a small business prepare a profit and loss statement?
Monthly is ideal. It's frequent enough to spot problems early and compare with the same month last year. Your accountant will also prepare an annual one for tax.
Is a profit and loss statement the same as an income statement?
Yes. Profit and loss statement, P&L, income statement and statement of profit or loss all refer to the same report.
Tekservix Team
The team behind Tekservix
The Tekservix Team builds and supports Tekservix: WhatsApp and SMS APIs, AI tools, invoicing, PDF and SEO tools for growing businesses. We write practical, tested guides based on what we see our customers do every day.
More articles from the Tekservix Team